

 RoseMarie Keogh-Smyth Makes Money Human
Home»Finance»U.S. Manufacturing Sector Faces Contraction Amid Rising Costs and Labo…
U.S. Manufacturing Sector Faces Contraction Amid Rising Costs and Labor Shortages
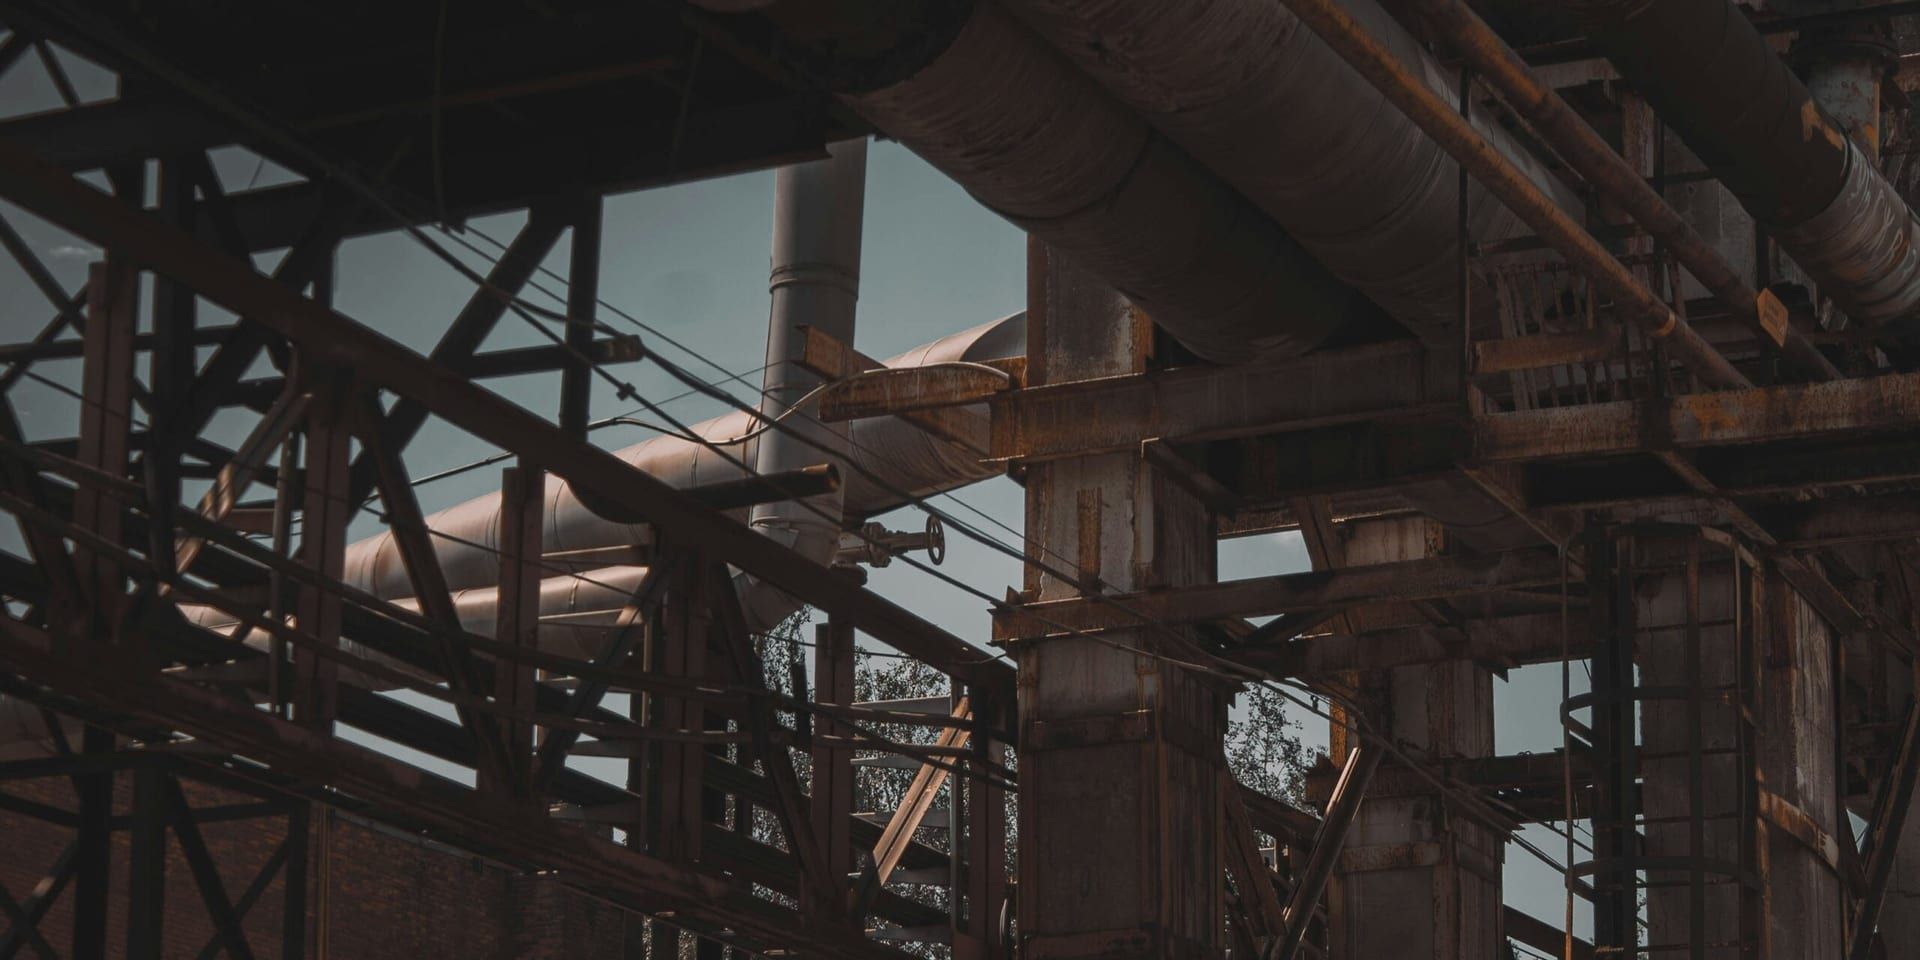
This week, new data confirmed that the U.S. manufacturing sector is experiencing a slowdown, marking the first contraction in nearly two years. According to the Institute for Supply Management (ISM), the purchasing managers’ index (PMI) fell below the neutral 50-mark, signaling a reduction in manufacturing activity. Several factors are contributing to this downturn, including rising input costs, a tight labor market, and the ongoing effects of the Federal Reserve’s interest rate hikes. These challenges are placing significant pressure on manufacturers, as high raw material prices and labor shortages continue to erode profit margins.
The contraction in manufacturing has been particularly felt in industries like automotive, steel, and electronics, which have long been pillars of U.S. manufacturing output. Companies such as General Motors and Caterpillar have reported lower-than-expected earnings, citing persistent supply chain issues and increased costs of production. These sectors are grappling with the rising prices of raw materials and the growing expense of wages, which have contributed to shrinking profit margins. For manufacturers, the combination of these factors has created a challenging environment, with many firms forced to make difficult decisions about pricing and production strategies.
In response to these pressures, manufacturers have been increasing the prices of their goods to maintain profitability. However, this strategy has not been without consequences, as higher prices are dampening consumer demand, particularly for durable goods. As input costs rise and profit margins tighten, manufacturers are increasingly turning to automation to offset rising labor costs and improve productivity. While automation offers long-term benefits, the upfront costs and technological investment required are significant, and not all manufacturers have the resources to implement such changes on a large scale.
The labor market continues to be a major point of frustration for manufacturers. Many companies report difficulty in finding skilled workers, particularly in fields like manufacturing engineering, electronics, and machinery operation. This shortage of skilled labor has further exacerbated production delays and limitations, as companies struggle to meet demand with a smaller pool of qualified workers. The tight labor market has also driven wages higher, which, while beneficial for workers, has increased operational costs for manufacturers.
Despite these ongoing challenges, some manufacturers are managing to thrive by diversifying their product offerings and targeting high-demand markets. Companies in the automotive sector, for example, are pivoting toward electric vehicles (EVs) and other clean energy products to capitalize on growing consumer interest in sustainability and green technology. Tesla, in particular, has reported strong earnings, driven by increased demand for its electric vehicles. While the broader automotive industry faces headwinds due to supply chain disruptions and higher production costs, Tesla’s focus on innovation and EV production has allowed it to continue growing in a difficult market.
Similarly, companies in the renewable energy sector are benefiting from a shift toward sustainable products. As governments and businesses continue to invest in clean energy solutions, manufacturers producing solar panels, wind turbines, and other renewable energy technologies have seen increased demand. This diversification strategy has allowed some companies to remain resilient, even as traditional manufacturing sectors struggle to keep pace with rising costs and labor shortages.
On the flip side, companies in the logistics and transportation sectors have fared better than their manufacturing counterparts. Firms like FedEx have reported stronger-than-expected earnings, largely driven by the sustained demand for e-commerce. The rapid growth of online shopping has led to an increase in the volume of goods that need to be delivered, fueling demand for shipping and logistics services. This shift in consumer behavior toward online shopping and home delivery has allowed transportation companies to perform well despite broader economic challenges.
As 2024 draws to a close, analysts are closely monitoring the manufacturing sector to determine whether the contraction is indicative of a broader economic slowdown or simply a temporary setback. While manufacturing is a critical component of the U.S. economy, its performance can be volatile, and some experts suggest that the slowdown could be a direct result of high inflation and the Federal Reserve’s tightening monetary policy. If demand for durable goods continues to falter and labor market conditions remain tight, the slowdown could extend into 2025, impacting economic growth.
However, there is hope that the slowdown may be short-lived. As inflation pressures ease and supply chain disruptions begin to resolve, manufacturing activity could rebound, particularly in sectors like electric vehicles and renewable energy, where demand remains strong. For now, manufacturers are focusing on navigating the challenges of the current environment, adjusting their strategies to meet evolving market conditions, and hoping that economic stability will return in the coming months.

Leadr Magazine Contributor
Ivan Petrosyan
Covers global markets and corporate finance, mapping the trends moving capital across borders.
This article features partner, contributor, or branded content from a third party. Members of the Leadr Magazine editorial staff were not involved in the creation of this content. All views and opinions are those of the contributor alone.
Related Posts
More from Finance
- Fed Faces Critical Rate Hike Decision as Inflation Pressures Persist
- Retailers Brace for Tough Holiday Season as Inflation and Rising Costs Strain Consumer Spending
- U.S. Job Market Defies Economic Challenges, Showing Record Hiring in November 2024
- Major M&A Deals Signal Strong Corporate Activity Amid Economic Uncertainty
- U.S. Economy Slows as GDP Growth Rate Declines in Q3 2024
- US Financial Markets Drop as January Jobs Report Signals Strong Labor Market Amid Inflation Woes
- The U.S. financial markets took a sharp downturn on January 19, 2024, following a string of disappointing earnings reports from major retailers, signaling that consumer demand remains weak as inflation continues to strain household budgets. The news sparked concerns that the economic recovery could be slower than anticipated, particularly as persistent inflation and high interest rates continue to weigh on both businesses and consumers. Retail giants such as Walmart, Target, and Macy’s reported lower-than-expected earnings for the fourth quarter of 2023, citing softer-than-anticipated holiday sales. The results reflect a shift in consumer behavior, as rising prices on essentials like food, fuel, and housing have forced many Americans to scale back spending on discretionary items. Some retailers also warned of slower growth in 2024 as inflation remains entrenched and borrowing costs rise. The weak retail earnings sent shockwaves through the broader market, with the S&P 500 falling 1.4%, the Nasdaq Composite dropping 1.9%, and the Dow Jones Industrial Average losing 1.2%. The declines were led by consumer discretionary stocks, with notable losses in retail and technology sectors, which are sensitive to changing consumer spending patterns. Investors now fear that a prolonged period of weak retail performance could signal broader economic slowdown. In the bond market, U.S. Treasury yields continued to rise, with the 10-year U.S. Treasury note hitting 4.7%, reflecting heightened expectations of further Federal Reserve rate hikes. Higher bond yields have already caused mortgage rates to stay above 7%, leading to a cooling of the housing market and raising concerns about the broader economy’s ability to sustain growth in a high-interest-rate environment. The disappointing retail earnings come on the heels of continued inflationary pressures. The latest data from the Consumer Price Index (CPI) and Producer Price Index (PPI) reports showed that while inflation has moderated from the 2022 highs, it remains well above the Federal Reserve’s 2% target. This persistent inflation, particularly in food and energy, continues to squeeze consumer spending and is expected to keep the Fed on a path of restrictive monetary policy throughout 2024. Retailers’ struggles reflect a broader trend, as businesses across sectors have been grappling with higher input costs, reduced consumer confidence, and the challenges of passing on price hikes to customers without significantly affecting demand. Consumer spending, a key driver of U.S. economic growth, has been slower to recover than expected, and many analysts are revising their growth forecasts for 2024 in light of the latest earnings reports. With the Fed’s rate hikes still keeping borrowing costs high, businesses are facing a higher cost of capital, which could further dampen expansion and investment in the coming months. Additionally, the ongoing inflationary environment is making it difficult for many households to maintain their previous levels of spending, particularly on non-essential goods. Geopolitical risks continue to complicate the economic outlook, with global tensions—particularly between the U.S. and China—potentially disrupting trade flows and adding further uncertainty to the market. The ongoing conflict in Ukraine also remains a source of volatility, particularly in energy markets, which could exacerbate inflationary pressures. Looking ahead, market participants are closely watching the next Federal Reserve meeting, scheduled for the end of January, for any signals on the central bank’s policy stance moving forward. While inflation remains stubbornly high, the weak retail earnings could push the Fed to reconsider its path of aggressive tightening, though many analysts believe the central bank is unlikely to ease until inflation is brought more firmly under control. For now, the U.S. financial markets are navigating a period of heightened uncertainty, with disappointing retail earnings, persistent inflation, and high borrowing costs casting a shadow over the economic outlook. The risk of a slowdown in consumer spending is a key concern for investors, and further market volatility seems likely as the year unfolds.
- US Financial Markets Plunge as Retail Earnings Disappoint Amid Persistent Inflation
- US Financial Markets Slump After Producer Price Index Shows Stubborn Inflation
- US Financial Markets Fall as Retail Sales Drop and Inflation Concerns Persist