

 Brad Sugars: Transforming Entrepreneurship Through Proven Systems, Business Growth, and Financial Freedom
Home»Finance»Federal Reserve Survey Shows Higher Median Family Income Alongside Ris…
Federal Reserve Survey Shows Higher Median Family Income Alongside Rising Debt-Payment Pressure
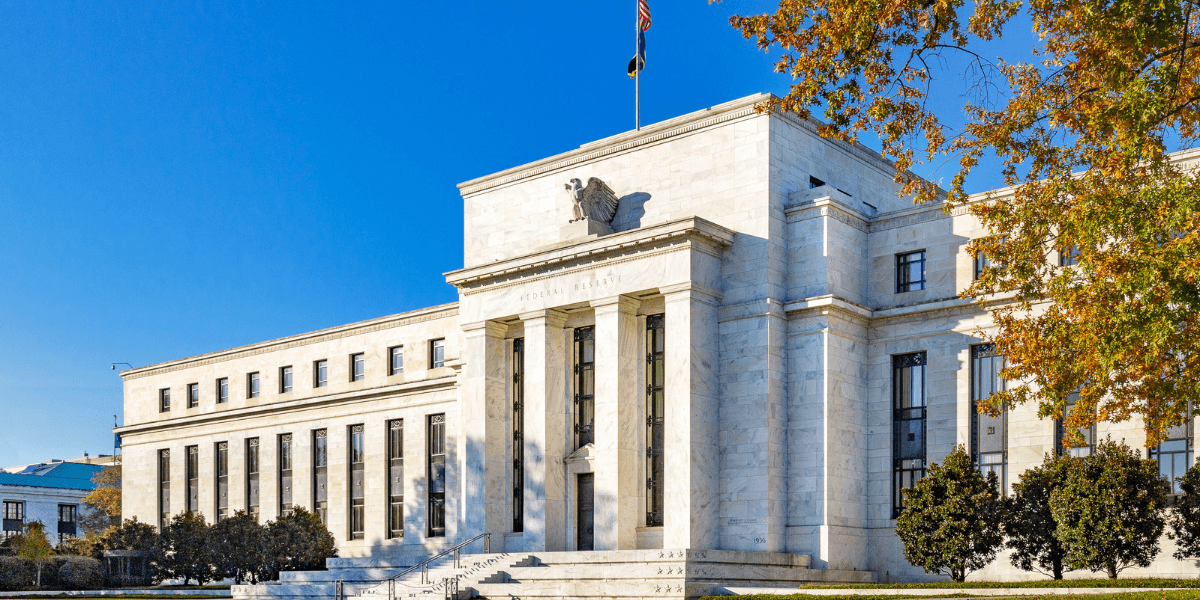
The Federal Reserve released its 2025 Survey of Consumer Finances, offering a detailed assessment of American households’ income, wealth, borrowing and financial vulnerability.
A Detailed Picture of Household Finances
The Federal Reserve Board published the results of its latest Survey of Consumer Finances on October 9. The survey, conducted every three years since 1989, provides a nationally representative view of household financial conditions, including assets, debts, income and banking behavior.
The findings showed that real median family income rose 7% between the 2022 and 2025 surveys, reaching $82,200. Real mean family income, however, fell 6% to $145,200 over the same period.
The difference between median and mean income matters. Median income represents the midpoint of the distribution, while mean income is an average that can be influenced by households with particularly high incomes. Their different movements suggest that the overall picture cannot be summarized by a single figure.
The survey also found that real median family net worth increased 2% to $215,900, while real mean net worth rose 7% to $1.24 million.
Wealth and Income Tell Different Stories
Income measures the money households receive over a period, while net worth measures the value of assets after subtracting liabilities. A family can have substantial wealth but limited current income, or earn a high income while carrying significant debt.
The survey’s results offer policymakers and business leaders a way to examine these differences. Household financial resources influence consumer spending, access to credit, the ability to absorb unexpected expenses and long-term economic security.
The Federal Reserve reported that most families across income and net-worth distributions experienced increases in median and mean wealth between the surveys. However, the overall figures do not mean that every household became financially stronger.
Economic conditions can vary considerably by age, income, homeownership, employment and existing debt obligations. National averages and medians help establish broad patterns, but they do not describe every household’s circumstances.
Debt Payments Become a Key Concern
One of the survey’s important findings concerned the share of families facing substantial debt-payment obligations relative to income.
The proportion of families whose debt payments exceeded 40% of their income increased from 6.5% in 2022 to 8.6% in 2025. The Federal Reserve said the figure had returned to a level last seen in the 2013 survey.
This measure provides insight into financial pressure because a large share of income committed to debt payments can leave households with less flexibility to cover other expenses.
The survey also found that approximately 77% of families had some form of debt, broadly unchanged from 2022. Median and mean outstanding debt also remained unchanged over the period.
These findings demonstrate why the prevalence of debt and the burden of servicing it are different measures. The proportion of households carrying debt may remain stable even as the share facing particularly high payment obligations increases.
Homeownership and Housing Wealth
The homeownership rate stood at 66% in 2025, approximately unchanged from 2022. For families owning homes, median net housing value—the value of a home minus home-secured debt—rose from $218,900 to $230,000.
Housing wealth is an important component of household balance sheets. A home can represent a major asset, but ownership also involves mortgage payments, maintenance, insurance, taxes and other expenses.
Changes in net housing value can affect household wealth without necessarily producing additional cash for everyday spending. Homeowners may have equity in a property while still facing substantial monthly obligations.
For businesses connected to housing, consumer finance and retail, these distinctions matter when evaluating demand and financial resilience.
Retirement and Market Participation
The survey found that participation in retirement plans was slightly higher, at approximately 65%, including account-based plans, individual retirement accounts and defined-benefit plans.
Participation in the stock market declined from 58% in 2022 to 56% in 2025. Among families that held stocks, median holdings increased 36%, from $56,900 to $77,400.
These statistics describe different dimensions of household financial participation. The share of families holding an asset does not reveal the amount held by each participant, while balances can change because of contributions, withdrawals and market movements.
Implications for Leaders and Policymakers
The survey provides evidence that household finances are not moving uniformly across all measures. Median income and wealth increased, but mean income declined and a larger proportion of families faced debt payments exceeding 40% of income.
For business leaders, household balance sheets can help explain differences in consumer resilience and spending capacity. For policymakers and researchers, the results provide a basis for examining how income, assets and debt interact across the population.
The findings are not a forecast of future consumer demand. Instead, they establish a detailed statistical picture of family finances during the period covered by the survey.
The broader lesson is that income growth alone does not fully describe financial security. Household wealth, housing costs, borrowing obligations and access to retirement resources also shape families’ ability to manage economic uncertainty.

Leadr Magazine Contributor
Ivan Petrosyan
Covers global markets and corporate finance, mapping the trends moving capital across borders.
This article features partner, contributor, or branded content from a third party. Members of the Leadr Magazine editorial staff were not involved in the creation of this content. All views and opinions are those of the contributor alone.
Related Posts
Brad Sugars: Transforming Entrepreneurship Through Proven Systems, Business Growth, and Financial Freedom How Samka Keranovic Brings Leadership Experience to Desert Roots Wellness
 Castaways Bistro: Punta Cana Paradise